 WhatsApp Us Now

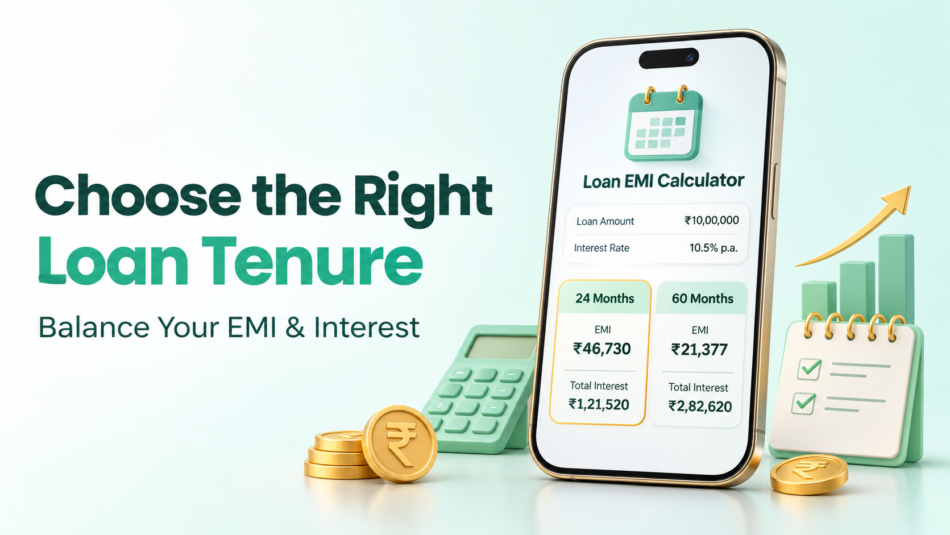
Ever signed up for a loan because the monthly EMI looked tiny, only to realise later how much extra you were paying? It happens more often than you’d think. The culprit is usually one small choice: your personal loan tenure.
It looks like a minor box to tick on the application form. It isn’t. Let’s talk about how to pick it wisely.
What Is Personal Loan Tenure?
Tenure is simply the time you take to repay your loan. Most lenders offer anywhere between 12 and 60 months. Shorter means a bigger EMI but less interest. Longer means a smaller EMI but more interest over time.
Read at: Instant Personal Loan Online: How to Get a Personal Loan in India (Without the Headache)
Short vs Long Tenure: A Quick Example
Suppose you take a loan of ₹2,00,000 at an interest rate of 15%.
- 2 years: EMI would be around ₹9,700 and the total interest would be ₹32,700.
- 5 years: EMI would be ₹4,750 and the total interest would be ₹85,500.
It is the same amount of money, but about ₹52,000 more is going into the pockets of the bank. The low EMI might appear to be a relief, but at what cost?
How to Choose the Right Repayment Period
Review your budget
The sum total of your rent, utilities, grocery expenses, and other EMIs should be calculated. A good tip here is to have no more than 40% of your income diverted towards EMIs. Based on that, select the shortest tenure possible.
Evaluate the stability of your income
If you get a fixed salary, then you can go for a shorter tenure without any problem. However, for those whose income fluctuates like freelance workers or businessmen, a bit longer tenure may do well.
Match the tenure to the purpose
A phone upgrade or a small medical bill doesn’t need a five-year loan. A bigger expense like a home renovation may justify more time.
Check prepayment rules
Some lenders allow part-payment or early closure at low or no charges. That lets you choose a moderate tenure and close the loan sooner when extra cash comes in.
Try an EMI calculator
Test a few tenures and watch how the EMI and total interest change. It takes two minutes and can save you thousands.
Personal Loan Approval and Documents Required
Tenure is only one part of the picture. For smooth personal loan approval, lenders look at your credit score, income, and current debts. A score of 750 or above usually helps.
The documents required for personal loan are fairly basic: PAN card, Aadhaar, recent salary slips or income proof, and bank statements. Keep them ready and the process moves much faster.
Why an NBFC Instant Loan Is So Popular
An NBFC instant loan usually means digital checks, less paperwork, and quicker decisions. You can apply for instant personal loan online, compare tenures, and see your EMI instantly, all without visiting a branch.
Final Thoughts
The right tenure is the one your budget can carry comfortably today without costing you too much tomorrow. Be honest about your expenses, test a few options, and don’t let a small EMI fool you.
When you’re ready, the KredBharat loan app makes it easy to explore flexible repayment options and apply with confidence. Visit KredBharat and find a tenure that fits your life.
FAQs
What would be the best tenure for taking out a personal loan?
It all depends upon your earnings and needs. 2 to 3 years tenure is recommended for most people.
Which would be better-a short-term or long-term tenure?
Shorter tenure helps save money on interest; however, EMI would be higher in such a case.
Is it possible to alter the tenure in case of personal loans?
Yes, in some cases, you might be able to do that. But only under part prepayment or restructuring.
What are the necessary documents for getting a personal loan?
PAN card, Aadhaar card, income statement, and bank statement.


